



Banking & Finances
Taxes for foreign property owners in Spain in 2026

Updated: October 2026
Owning a home in Spain means paying Spanish taxes on it – even if you never rent it out and live abroad. Which taxes apply depends on whether you are a tax resident in Spain or not. This guide explains the main property taxes in 2026 and the deadlines you must not miss.
Taxes every owner pays
- IBI (property tax): a yearly local tax paid to the town hall, based on the cadastral value. Usually a few hundred euros a year.
- Rubbish collection (basura): a local fee in most towns.
- Community fees: not a tax, but compulsory if your home is in a building or urbanisation.
Non-residents: the yearly imputed income tax
If you are not a Spanish tax resident and do not rent out your home, Spain still taxes a notional (“imputed”) income from it through the non-resident income tax (IRNR), filed on form 210.
- The imputed income is 1.1% or 2% of the cadastral value, depending on whether the value was recently revised.
- The tax rate is 19% for EU/EEA residents and 24% for everyone else.
- The return for a given year is due by 31 December of the following year.
If you rent out your property
- Non-residents from the EU/EEA pay 19% on the net rental income – costs such as IBI, community fees, repairs and interest can be deducted.
- Non-residents from outside the EU/EEA pay 24% on the gross rental income, without deductions.
- Rental income is declared quarterly on form 210.
- Tourist and seasonal lets must be registered (regional tourist licence and, since 2025, the national rental register). In many buildings, the community must now approve new tourist flats.
Tax residents in Spain
If you live in Spain more than 183 days a year, you are a tax resident and pay Spanish income tax (IRPF) on your worldwide income. Your main home has no imputed income, but second homes do. Rental income is taxed at the normal progressive rates, with a reduction for long-term rentals of a main home.
Wealth tax
Wealth tax (Impuesto sobre el Patrimonio) and the national solidarity tax on large fortunes only affect people with high net assets. Allowances and regional rules differ a lot – Andalusia, for example, fully relieves regional wealth tax, but the national solidarity tax can still apply above €3 million. Get advice if your assets in Spain are large.
When you sell
- Capital gains are taxed at 19% for non-residents.
- The buyer must withhold 3% of the price and pay it to the tax office on your behalf. You reclaim any overpayment on form 210.
- The town hall also charges plusvalía municipal, a local tax on the increase in land value.
FAQ: property taxes in Spain
Do I pay tax if I only use my Spanish home for holidays?
Yes. As a non-resident you pay IBI and the yearly imputed income tax on form 210, even if you never rent it out.
What happens if I forget to file form 210?
The tax office can charge late-filing surcharges and interest. It is common for non-residents to use a gestor or tax representative to file every year.
Can I still get a golden visa by buying property?
No. Spain abolished the golden visa through property investment in April 2025.
Do I need a Spanish tax number?
Yes. You need a NIE to buy, own and sell property and to file your taxes.
Useful links
- Agencia Tributaria – Spanish tax office
- How to handle a Spanish tax inspection
- Getting a mortgage in Spain
Disclaimer: This article is general information only and not tax advice. Tax rules, rates and regional allowances change – always speak to a qualified tax advisor about your situation.
Published: August 2025
Navigating the Spanish tax system can be challenging for expats, especially when facing a tax audit or inspection. Understanding your rights, obligations, and the process is key to avoiding stress and costly mistakes. Here’s a practical guide for foreigners in Spain on how to handle tax audits and what to expect if the Spanish tax authorities (Agencia Tributaria) come knocking.
Why you might be audited in Spain
Spanish tax authorities select cases for audit based on random checks, discrepancies in your tax return, high-value transactions, or information from other countries. Common triggers include unreported income, sudden changes in declared assets, or inconsistencies with bank data.
The audit process explained
- Notification: You’ll receive an official letter (“requerimiento”) by post or via your digital mailbox (Agencia Tributaria).
- Document request: You must provide supporting documents (bank statements, contracts, invoices, proof of residence, etc.) within the deadline stated.
- Meeting or inspection: Sometimes you’ll be invited for an interview or an inspector may visit your home or business.
- Resolution: The authorities will issue a decision—either closing the case or making an adjustment (which may include fines or back taxes).
- Appeal: You have the right to appeal decisions through administrative or legal channels.
Key tips for expats facing a tax audit
- Keep all tax-related documents for at least 4-5 years.
- Respond promptly and politely to any official requests.
- Use a registered tax advisor if you’re unsure—many specialize in expat cases.
- Don’t ignore letters from Agencia Tributaria, even if you’re abroad.
- Be honest—deliberate fraud is punished severely in Spain.
Common documents you might need
- Bank statements and account summaries (Spanish and foreign)
- Employment contracts or freelance invoices
- Proof of residency (empadronamiento, rental contracts, utility bills)
- Declarations of overseas assets (Modelo 720)
- Receipts for deductible expens
FAQ: Spanish tax audits and inspections
How will I know if I’m being audited?
You’ll receive an official notification by post or digitally from Agencia Tributaria.
Do I need to speak Spanish to handle an audit?
It helps, but you can use a certified advisor or translator if needed.
How long does a tax audit take?
Most audits are resolved within a few months, but complex cases can take longer.
What happens if I ignore the audit?
Ignoring official requests can lead to fines, asset freezes, or legal action.
Can I appeal a tax decision?
Yes, you have the right to appeal administratively or through the courts.
Are foreigners targeted more than locals?
Not specifically, but expats with foreign income or assets may get extra scrutiny.
What is Modelo 720?
It’s a declaration of overseas assets, required for residents with more than €50,000 abroad.
Do I need a lawyer for a tax audit?
Not always, but complex cases or appeals benefit from professional help.
What documents should I keep?
All tax returns, bank statements, contracts, and proof of residency for at least 4-5 years.
Can I get help in English?
Many tax advisors in Spain speak English and are experienced with expat cases.
Disclaimer: This article is for informational purposes only. Always consult a professional for specific tax advice.
Updated: October 2026
A Spanish bank account is one of the first things you need when you move to Spain. You need it for your salary or pension, rent, electricity, internet, phone contracts and paying taxes. This guide explains which account types exist in 2026, what documents banks ask for, and how to open an account step by step as a foreigner.
Why you need a Spanish bank account
- Receiving your salary or pension.
- Paying rent, utilities and community fees by direct debit (domiciliación).
- Setting up internet and mobile phone contracts – many providers want a Spanish IBAN.
- Paying taxes and social security, and receiving refunds from the tax office.
- Applying for a mortgage later on.
Types of bank accounts in Spain
- Resident account: for people who live in Spain and have a NIE or TIE. It gives full access to banking services and is usually cheaper.
- Non-resident account: for people who live in Spain less than 183 days a year, for example holiday home owners. Banks ask for a non-residence certificate and fees are often higher.
- Basic payment account (cuenta de pago básica): every person legally living in the EU has the right to this simple account. The fee is capped at €3 per month, and it is free for people in a vulnerable financial situation.
- Online banks and fintechs: digital accounts with low fees, opened from your phone. Check that you get a Spanish IBAN (starting with ES) if you need it for direct debits.
Documents you need in 2026
- Valid passport or EU ID card.
- NIE number or TIE card. Many banks will not open a resident account without it – see how to get your NIE.
- Proof of address: rental contract, utility bill or empadronamiento certificate.
- Proof of income or activity: work contract, payslips, pension statement or self-employed registration.
- Your tax number from your home country (banks must report foreign tax residents).
- For non-resident accounts: a non-residence certificate, which the bank can often request from the police for you.
Because of anti-money-laundering rules, the bank will also ask where your money comes from and what you will use the account for. This is normal – answer clearly and bring documents if you plan to transfer larger amounts.
How to open a bank account – step by step
- Choose a bank. The big banks are Santander, BBVA, CaixaBank, Sabadell, Bankinter and Unicaja. Compare monthly fees, card costs and whether the app and staff work in English.
- Collect your documents from the list above.
- Apply online or in a branch. Many banks let you start online with video identification. Some still require a branch visit for foreigners.
- Sign the contract digitally or in the branch, and read the fee list (tarifas) before you sign.
- Activate the app and card. Set up online banking and add the account to your direct debits.
How to avoid high fees
- Many banks waive the monthly fee if your salary or pension is paid into the account, or if you use the card a few times a month.
- Check ATM fees – withdrawing cash at another bank’s ATM can cost money.
- Use Bizum (built into most Spanish bank apps) for free instant payments between people in Spain.
- For money from abroad, compare the bank’s exchange rate with services like Wise.
FAQ: bank accounts in Spain
Can I open a Spanish bank account before I move?
Some online banks and international branches let you start from abroad, usually as a non-resident account. Most traditional banks want a Spanish address and a NIE for a resident account.
Can I open an account without a NIE?
Sometimes – some banks open non-resident accounts with just a passport. For a resident account, a mortgage and most official paperwork you will need a NIE.
What does a bank account cost in Spain?
Usually between €0 and €15 per month. Many accounts are free if you pay in a salary or pension. A basic payment account costs at most €3 per month.
Can foreigners open a joint account?
Yes. Both account holders need to show identification and, for resident accounts, their NIE.
Are online banks a good option?
Yes, for everyday use and low fees. For a mortgage or in-person help, a traditional Spanish bank is usually better.
Can I get a mortgage as a non-resident?
Yes, but conditions are stricter – non-residents can usually borrow around 60–70% of the property value. Read our mortgage guide.
Useful links
- Banco de España – bank customer portal (fees, complaints, basic account)
- Get your NIE number
- Getting a mortgage (hipoteca) in Spain
Disclaimer: This article is for general information only and is not financial advice. Fees and requirements vary by bank – always check the bank’s current conditions.
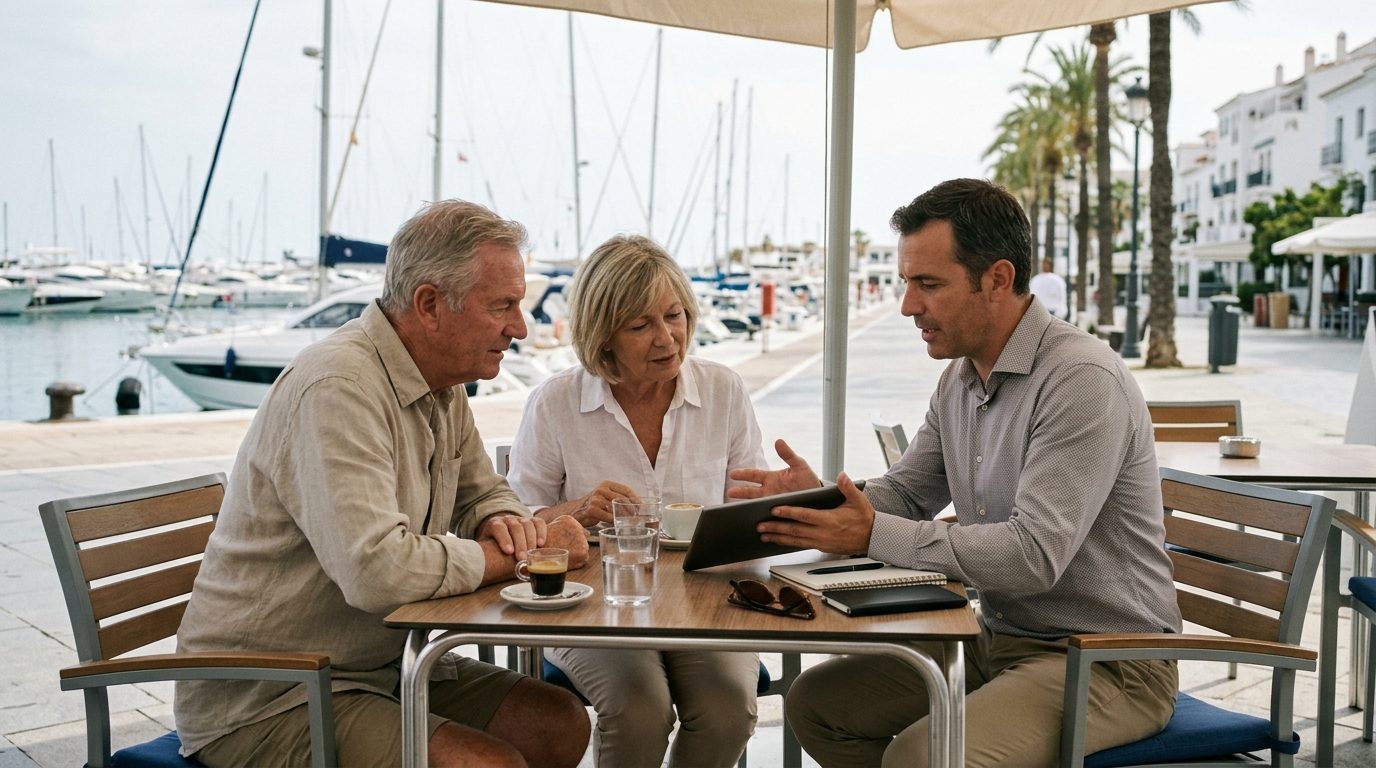
In 2026, Spanish banks are recommending a range of investment options, focusing on strategies that cater to both individual and corporate clients amidst an economic
environment marked by high interest rates and controlled risk levels.
Here are some key investment avenues that Spanish banks are encouraging their customers to consider:
Sustainable Investments:
Sustainability is a major theme, with banks like BBVA and CaixaBank emphasizing investment in environmentally and socially responsible portfolios.
This includes green bonds, sustainable funds, and companies with strong environmental, social, and governance (ESG) practices.
These products align with global trends towards responsible investing, especially as more clients look for ethical ways to grow their wealth
(BBVA CIB)(CaixaBank).
Real Estate:
Real estate continues to be a popular investment option in Spain, particularly for those looking for long-term appreciation or rental income.
Spain’s property market remains attractive to both local and foreign investors, especially in high-demand areas like Madrid, Barcelona, and coastal regions.
Some banks also offer specialized mortgage products to assist with real estate purchases
(SpainHow).
Time Deposits:
With rising interest rates, many customers are turning to time deposits (fixed-term savings accounts) for stable returns.
Banks have accelerated the pass-through of higher interest rates to time deposits, making them an attractive option for risk-averse investors looking for secure, short-term gains
(Scope Group).
Managed Portfolios and Digital Investment Platforms:
CaixaBank’s “Smart Money” service offers customers personalized, digital investment management.
These managed portfolios allow investors to diversify their holdings across various markets while adjusting for personal risk tolerance.
This service is growing in popularity due to its simplicity and the ability to tailor investments to individual financial goals
(CaixaBank).
Emerging Markets:
Despite global economic uncertainty, Spanish banks like BBVA and Santander recommend considering emerging market investments, particularly in regions with rising consumer loan portfolios. These markets, while riskier, offer higher growth potential compared to more mature economies
(Scope Ratings)(Scope Group).
In summary, Spanish banks in 2026 are focusing on sustainable investments, real estate, and digital-managed portfolios, while also highlighting the importance of time deposits
due to higher interest rates. These strategies provide a balanced approach to growth and risk management in a fluctuating economic landscape.

Tvmate Pro app & Streambox 4K media box for expats in Spain

The Spanish job market in 2026: sectors with the most opportunities for expats

Mental health support for expats in Spain: resources & tips

Understanding the tax system in Spain

Marbella guide: beaches, Puerto Banús and the old town

Andalucía: history, culture and places to visit
-
 Banking & Finances2 years ago
Understanding the tax system in Spain
-
 Tourist Info2 years ago
Marbella guide: beaches, Puerto Banús and the old town
-
 Tourist Info2 years ago
Andalucía: history, culture and places to visit
-
 Legal Requirements & Documentation2 years ago
How to get your Spanish NIE number in 2026 – step by step
-
 Safety & Emergency2 years ago
Terrorism threat level and safety in Spain
-
 Legal Requirements & Documentation2 years ago
Residency in Spain 2026: how to become a legal resident – step by step
-
 Employment2 years ago
Living on a small salary in Spain
-
 Legal Requirements & Documentation2 years ago
Work visa and work permit in Spain 2026 – which one you need and how to apply