

Insurance
Understanding insurance in Spain: a 2026 guide for expats
Health, car, home, life, travel and pet insurance in Spain explained: what is compulsory in 2026, brokers vs agents and how to compare policies.


Updated: October 2026
Insurance in Spain works a little differently from what many newcomers are used to: some covers are compulsory, some are tied to a mortgage or a visa, and others are simply very popular locally. This guide explains the main types of insurance, what is required by law in 2026, the difference between a broker and an agent, and how to compare policies without paying for cover you do not need.
What is compulsory and what is optional
| Insurance | Required? | Notes |
|---|---|---|
| Car (third-party liability) | Yes, for every vehicle registered in Spain | Even if the car is parked and not used |
| E-scooters and personal mobility vehicles | Yes, liability cover since January 2026 | Linked to a new DGT registry for these vehicles |
| Health | Only in some cases | Needed for some visas and residence permits if you are not in the public system |
| Home | Not by law | Building damage cover is required by mortgage lenders |
| Dogs (liability) | Only for potentially dangerous breeds so far | General obligation for all dogs awaits implementing rules |
| Life, travel, funeral, accident | No | Optional, but often sold with mortgages and loans |
Health insurance
If you work in Spain, are self-employed or receive a pension that gives you rights here, you are covered by the public health system; see our guide to healthcare for foreign residents. Many expats still add private cover to get faster specialist appointments and English-speaking doctors. Public waiting lists are real: the Ministry of Health reported an average wait of around 121 days for planned surgery at the end of 2025, with large differences between regions.

 Online pharmacy & parapharmacySkincare, vitamins, baby care and more – delivered in SpainShop now
Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.Learn more →(ad)
 Buying a home in Spain? Simulate your mortgageSee your monthly payment with Banco Sabadell’s mortgage simulator.Try the simulator →(ad)
 A bank account for autónomos in SpainCuenta Clara Autónomos: no commissions, free debit and credit cards, opened online.See the account →(ad)
 A European bank you open from your phonebunq: an EU-licensed bank with debit cards, managed fully in the app. Sign up in about five minutes.Get started →(ad)
 A mobile bank account with no commissionsB100, the mobile bank from Abanca: everyday account and free debit card, all in the app.Get the app →(ad)


If you apply for certain residence permits without access to the public system, such as non-lucrative residence, consulates and immigration offices usually require a private policy from an insurer authorised in Spain, with cover comparable to the public system and typically no co-payments and no waiting periods. Check the exact wording required before you buy; see our residency guide.
- Co-payment (copago): a small fee per visit; makes the premium cheaper.
- Waiting periods (carencias): time before some services are covered, often for maternity, surgery or hospital stays.
- Pre-existing conditions: often excluded; declare them honestly, or a claim can be refused.
- Age: premiums usually rise with age, and some insurers do not accept new customers above a certain age.
Car and e-scooter insurance
Every vehicle registered in Spain must have at least compulsory third-party liability insurance (seguro obligatorio), even if it is not driven. The common levels of cover are:
- Terceros: third-party liability only, the legal minimum plus usually legal defence.
- Terceros ampliado: adds items such as glass, theft and fire.
- Todo riesgo: fully comprehensive, also covering damage to your own car, often with an excess (franquicia) to lower the price.
Insurers price on your Spanish claims history, so ask your previous insurer abroad for a no-claims certificate, ideally translated. Since January 2026, owners of electric scooters and other personal mobility vehicles must also hold liability insurance under Law 5/2025, linked to a new DGT registry. For driving rules, see our driving licence guide.
Home, life and other common covers
Home insurance
Home insurance (seguro de hogar) is not compulsory by law, but if you have a mortgage the lender will require cover for damage to the building. You are not obliged to buy it from the bank; you can choose an equivalent policy elsewhere. In apartment blocks the community of owners normally insures the building, so owners often only need contents and liability cover. Tenants should consider contents and liability cover too; see our guide to renting in Spain.


Damage from floods, earthquakes and other extraordinary events is normally paid not by your insurer but by the Consorcio de Compensación de Seguros, a public body funded through a small surcharge included in most home and car policies. It also steps in for accidents caused by uninsured or unidentified vehicles. This is why having a valid policy matters even in a natural disaster.
Life, funeral and accident insurance
- Life insurance (seguro de vida): banks often push it with a mortgage. Compare it with independent offers, and check whether you can change policy later.
- Funeral insurance (seguro de decesos): very common in Spain, much more than in Northern Europe. It pays and organises the funeral, and some policies include repatriation of remains to your home country.
- Accident insurance: pays fixed amounts for injury or disability; popular with self-employed people and active retirees.
Travel and pet insurance
Annual multi-trip travel insurance suits residents who travel often. EU residents can use the European Health Insurance Card in other EU countries, but the European Commission stresses it is not a replacement for travel insurance. For dogs, the 2023 animal welfare law includes a liability insurance obligation, but it cannot be enforced until implementing regulations set the details; owners of potentially dangerous breeds already need liability cover, and some regions and towns set their own rules.
Broker, agent or bank?
You can buy insurance directly from an insurer, through an agent who represents one company (or a few), through a broker (corredor) who works independently with several insurers, or through your bank.
- Broker: can compare several insurers and move your policy if prices rise. Ask how they are paid, since commissions differ between companies.
- Agent: knows one insurer well and can be a direct contact when you claim, but offers less choice.
- Bank: convenient, but often more expensive and sometimes linked to better loan conditions. Do the maths before accepting.
Insurance distributors must be registered. In Andalusia the regional consumer service explains the register of agents and brokers, which is public and connected to the national register kept by the Dirección General de Seguros y Fondos de Pensiones (DGSFP).
How to compare policies
- Decide what you really need to cover, based on your residence status, home, car and family situation.
- Ask for the general and particular conditions (condiciones generales y particulares) and read the exclusions, not just the summary.
- Compare excesses, waiting periods, cover limits and whether you can choose your own doctor or repair shop.
- Check the renewal terms: most policies renew automatically each year, and you must give written notice before the renewal date if you want to cancel.
- Ask for documents in English if your Spanish is limited, but remember the Spanish version is usually the legally binding one.
The cheapest offer rarely gives the best protection. If a claim is refused, complain in writing to the insurer’s customer service department first; if that does not solve it, you can take the complaint to the DGSFP.
Useful links
- Consumo Responde (Junta de Andalucía): register of insurance agents and brokers
- RACE: what the Consorcio de Compensación de Seguros covers
- European Commission: what the EHIC covers
- Healthcare in Spain for foreign residents
- How to become a resident in Spain
FAQ: insurance in Spain
Which insurance is compulsory in Spain?
Third-party liability for cars and other motor vehicles, liability cover for e-scooters since January 2026, and liability for potentially dangerous dogs. Health insurance is required for some visas and permits.
Do I have to buy home and life insurance from my mortgage bank?
No. The lender can require building damage cover, but you can choose an equivalent policy from another insurer. Life insurance is optional, although banks may offer better loan terms if you take it.
Who pays for flood damage?
Damage from extraordinary events such as floods is usually paid by the Consorcio de Compensación de Seguros, but only if you have a valid home or car policy that includes its surcharge.
How do I cancel a policy in Spain?
Most policies renew automatically. Send written notice to the insurer before the renewal date, keep proof that it was received, and check the notice period in your conditions.
Disclaimer: This article is general information only and is not legal, financial or insurance advice. Rules, cover and prices can change – always read the policy conditions and check with the insurer or an authorised broker before you sign.


Insurance
Pet insurance in Spain: what is compulsory and what is worth having
Liability insurance for dogs, vet health insurance and accident cover in Spain: what the law says and what to check before you sign.
Updated: October 2026
Vets in Spain are generally good value compared with northern Europe, but an operation, a broken leg or a long illness can still cost several thousand euros. At the same time, Spain’s animal welfare law has made liability insurance for dogs a topic every owner should know about. This guide explains the different types of pet insurance in Spain, what is and is not compulsory, and what to check before you sign.
Is pet insurance compulsory in Spain?
The animal welfare law, Ley 7/2023, says that dog owners must have third-party liability insurance (seguro de responsabilidad civil) covering damage their dog causes to other people. However, the obligation depends on an implementing regulation that sets the minimum cover, and that regulation is still pending. Until it is approved, the general obligation is not yet enforced.
Online pharmacy & parapharmacySkincare, vitamins, baby care and more – delivered in SpainShop now
Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.Learn more →(ad)
Buying a home in Spain? Simulate your mortgageSee your monthly payment with Banco Sabadell’s mortgage simulator.Try the simulator →(ad)
A bank account for autónomos in SpainCuenta Clara Autónomos: no commissions, free debit and credit cards, opened online.See the account →(ad)
A European bank you open from your phonebunq: an EU-licensed bank with debit cards, managed fully in the app. Sign up in about five minutes.Get started →(ad)
A mobile bank account with no commissionsB100, the mobile bank from Abanca: everyday account and free debit card, all in the app.Get the app →(ad)
There are two important exceptions. Owners of potentially dangerous dogs (perros potencialmente peligrosos, such as certain breeds and large, powerful dogs) already need a municipal licence and liability insurance under the older law on dangerous animals. Some regions and town halls also have their own rules, so ask at your ayuntamiento when you register your dog.
Health insurance for vet bills is never compulsory. It is a personal choice, and for many owners it is about peace of mind.
The three types of cover
- Liability insurance (responsabilidad civil): pays if your dog bites someone, causes a traffic accident or damages property. It is often cheap and can sometimes be added to your home insurance – check whether your policy already includes pets.
- Vet health insurance (seguro de salud): pays part of your vet bills for illness and accidents, for example operations, hospital stays, tests and medicines. This is what most people mean by pet insurance.
- Accident-only cover: a cheaper option that only pays for injuries from accidents, not for illness.
What to check before you sign
- Age limits: many insurers only accept new pets up to a certain age, and premiums rise as the animal gets older. Insuring a young animal is usually easier and cheaper.
- Waiting periods (carencia): cover for illness often starts only after a few weeks. Accidents are usually covered sooner.
- Pre-existing conditions: illnesses your pet already has are normally excluded.
- Excess and co-payment: check how much you pay yourself per claim or per year.
- Annual limit: some policies cap what they pay per year or per condition.
- Choice of vet: some policies let you use any vet and claim the money back; others only work with partner clinics.
- Language: make sure you understand the policy and claims process. Ask for documents in English if your Spanish is not strong.
Health risks that make cover worth considering
Spain’s warm climate brings diseases that pets from northern Europe may never have met, such as leishmaniasis (spread by sandflies) and processionary caterpillars in pine areas. Treatment can be long and expensive. Our guide to moving to Spain with a dog or cat explains the main risks and how to prevent them.
Where to compare pet insurance
Ask your vet which insurers their clinic works with, and compare at least two or three quotes. For dogs, Petplan (ad) offers health and accident policies in Spain, and you can get a price online in a few minutes. Spanish banks and home insurers also sell pet cover, often as an add-on.
Useful links
- Ley 7/2023 on animal welfare (BOE, Spanish)
- Legal Today: why the dog insurance obligation depends on a regulation (Spanish)
FAQ: pet insurance in Spain
Do I have to insure my dog in Spain?
The animal welfare law requires liability insurance for dogs, but the obligation depends on a regulation that has not yet been approved. Owners of potentially dangerous dogs already need a licence and insurance. Check local rules at your town hall.
Do I need insurance for my cat?
No. The liability insurance in the animal welfare law is for dogs. Health insurance for cats is optional.
Does my home insurance cover my pet?
Some home insurance policies include liability for damage caused by pets, or let you add it. Vet bills are usually not included. Check your policy or ask your insurer.
Can I insure an older pet?
Often yes, but many insurers have a maximum age for new policies and charge more for older animals. Pre-existing conditions are usually excluded.
Disclaimer: This article is general information only and is not legal or insurance advice. Rules and policy terms change – check the conditions with the insurer and local rules with your town hall before you decide.
Housing & Utilities
Home insurance in Spain explained for owners, tenants and holiday-home owners
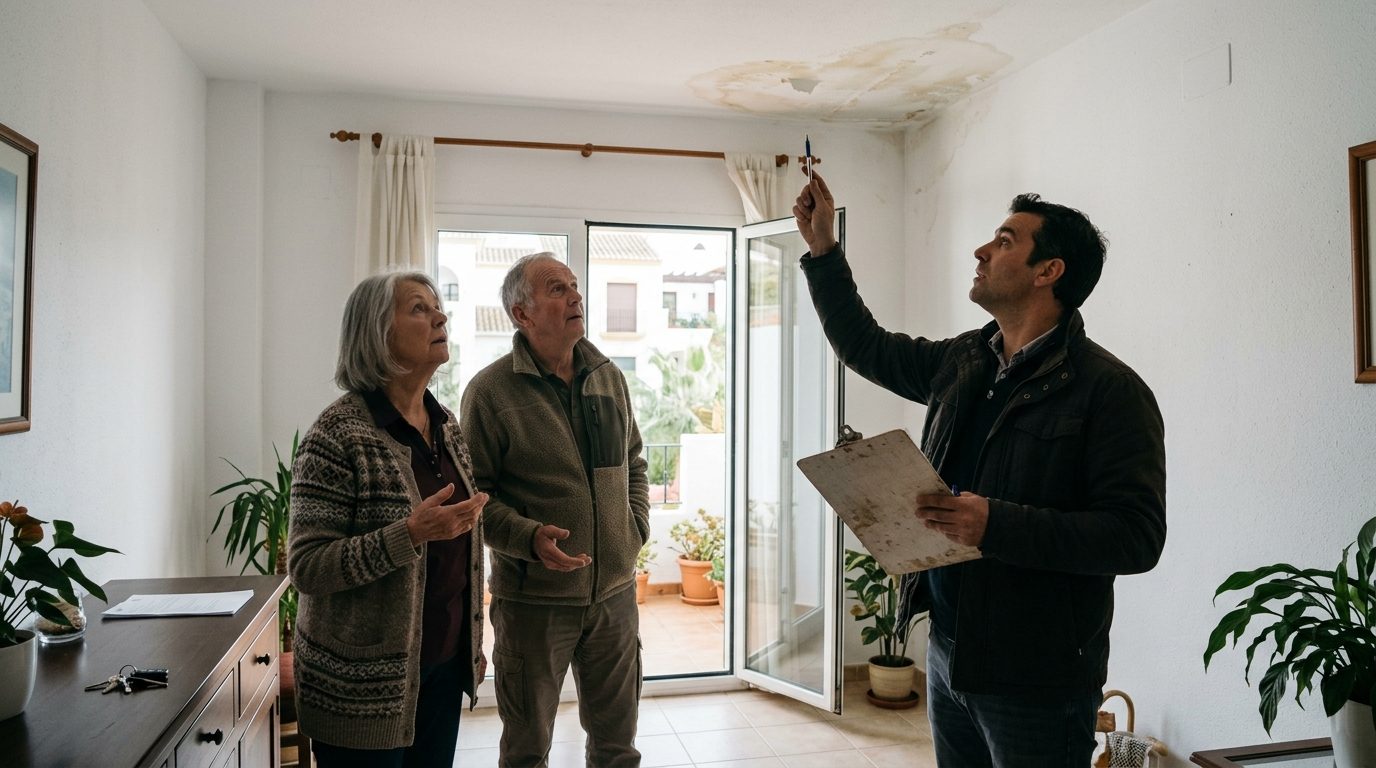
How seguro de hogar works in Spain: building vs contents, community and mortgage rules, flood cover via the Consorcio and how to claim.
Updated: October 2026
Home insurance in Spain, called seguro de hogar, is not compulsory for most private households, yet nearly every homeowner and many tenants have it. This guide is for expats who own, rent or keep a holiday home in Spain. It explains what a policy covers, how it fits with your community’s building insurance and your mortgage, who pays after floods and storms, and how to make a claim.
If you are new to Spanish insurance in general, start with our overview of insurance in Spain.
Online pharmacy & parapharmacySkincare, vitamins, baby care and more – delivered in SpainShop now
Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.Learn more →(ad)
Buying a home in Spain? Simulate your mortgageSee your monthly payment with Banco Sabadell’s mortgage simulator.Try the simulator →(ad)
A bank account for autónomos in SpainCuenta Clara Autónomos: no commissions, free debit and credit cards, opened online.See the account →(ad)
A European bank you open from your phonebunq: an EU-licensed bank with debit cards, managed fully in the app. Sign up in about five minutes.Get started →(ad)
A mobile bank account with no commissionsB100, the mobile bank from Abanca: everyday account and free debit card, all in the app.Get the app →(ad)
Continente and contenido: the two halves of a policy
Every Spanish home policy is built around two insured values. Getting them right is the most important part of buying cover.
- Continente (building): walls, floors, roof, fixed installations such as plumbing and wiring, fitted kitchens and bathrooms. The value should be the cost of rebuilding, not the market price of the property.
- Contenido (contents): furniture, appliances, clothes, electronics and personal belongings. Jewellery and valuables are usually limited unless you declare them.
Most policies also include responsabilidad civil (third-party liability), for example if water from your flat damages the neighbour’s ceiling, plus assistance services such as emergency plumbers and locksmiths.
Watch out for infraseguro (underinsurance). If you declare less than the real value, the insurer can reduce any payout in proportion. Many insurers offer a “valor total” option or automatic indexation to avoid this.
Owners, tenants and the community policy
If you own a flat
In an apartment block, the community of owners (comunidad de propietarios) normally insures the common parts: facade, roof, staircases, lifts and shared pipes. The national property law does not make this insurance compulsory everywhere, but some regions do. In the Madrid region and the Valencian Community, for example, residential buildings must be insured against fire and third-party damage. In practice most communities have a policy, and the premium is part of your community fees.
Ask the administrator for a summary of the community policy so you know where it stops. Your own policy should then cover the inside of your flat, your contents and your personal liability. A burst pipe in your bathroom that floods the flat below is normally your responsibility, not the community’s.
If you own a house
For a detached or semi-detached house you insure everything yourself: building, garden walls, pool and contents. Check that outdoor items, pool equipment and solar panels are listed, because some basic policies exclude them.
If you rent
The landlord is responsible for insuring the building. As a tenant you only need a contents and liability policy, which is usually inexpensive. Liability cover is the key part: if you cause a leak or a fire, you could otherwise be asked to pay for the damage. Our guide to renting in Spain as a foreigner covers contracts, deposits and your rights.
Home insurance and your mortgage
If you buy with a Spanish mortgage, the bank can require damage insurance on the property for the life of the loan. Under the mortgage credit law (Law 5/2019), however, it cannot force you to buy that policy from the bank or from an insurer it chooses.
- You can present a policy from another company with equivalent cover, both at signing and at each renewal.
- The bank may not charge you for reviewing that alternative policy, nor worsen the loan terms because you chose it.
- The bank can offer a lower interest rate if you take its insurance. Compare the total cost over several years before you accept.
The Banco de España explains these rights in its customer portal (Spanish).
Floods, storms and the Consorcio de Compensación de Seguros
Spain has a public body that pays for damage from extraordinary events: the Consorcio de Compensación de Seguros. It is funded by a small surcharge included in home, car and other property policies. It covers, among other things:
- Extraordinary floods, including sea surges.
- Earthquakes, tsunamis and volcanic eruptions.
- Atypical cyclonic storms, including tornadoes and wind gusts above 120 km/h.
- Terrorism, riots and civil unrest.
The catch is simple: you only get Consorcio compensation if you have a valid policy covering the damaged property and your premium is paid. A house with no insurance gets nothing from the Consorcio after a flood. The excess that applies to businesses has been removed for private homes and residential communities. Ordinary storms, rain coming through a roof and rising groundwater are not “extraordinary” and are handled, if at all, by your own insurer under your policy terms.
To claim from the Consorcio, you, your insurer or your broker file a claim online, by phone or by email. RACE summarises how the Consorcio works, and Legálitas explains what it covers after floods.
Holiday homes and empty properties
If your Spanish home is empty for months at a time, tell the insurer and choose a policy designed for a second home (segunda residencia). Standard policies often restrict theft and water damage cover when a property is unoccupied for a long continuous period, so read the clause on deshabitación carefully.
- Security: some insurers ask for a reinforced door, window bars or an alarm for theft cover.
- Water: turning off the main tap when you leave can be a policy condition and prevents most leaks.
- Holiday letting: a normal home policy rarely covers paying guests. If you rent to tourists, you need specific cover, and several regions require liability insurance for licensed tourist rentals. Check your regional rules and tell your insurer.
Owners of second homes also have running costs and local taxes to budget for; see our guide to property taxes for foreign owners.
How to make a claim
- Limit the damage: stop the leak, secure doors and windows, and keep damaged items if it is safe to do so.
- Document everything: photos, videos, receipts and a list of what was damaged or stolen.
- Report a theft to the police: insurers need the police report (denuncia) for burglary claims.
- Notify the insurer within 7 days: this is the general deadline in the Spanish insurance contract law, unless your policy gives longer. Most insurers accept claims by app, phone or online.
- Meet the loss adjuster: for larger claims the insurer sends a perito to assess the damage. Do not throw away damaged items or start major repairs before the visit unless it is urgent.
If the insurer rejects your claim or offers too little, complain in writing to its customer service department first. If that fails, you can escalate to the insurance supervisor, the Dirección General de Seguros y Fondos de Pensiones.
Useful links
- Banco de España: can the bank impose its insurance with a mortgage? (Spanish)
- RACE: what the Consorcio de Compensación de Seguros is (Spanish)
- Legálitas: what the Consorcio covers (Spanish)
- Understanding insurance in Spain
- Renting a home in Spain as a foreigner
- Property taxes for foreign owners in Spain
FAQ: home insurance in Spain
Is home insurance compulsory in Spain?
Not for most private homes. It becomes a requirement if you have a mortgage (damage cover on the building), and some regions require residential buildings to be insured against fire and third-party damage.
Do I have to buy home insurance from my mortgage bank?
No. The bank can require cover but must accept an equivalent policy from another insurer, both at signing and at renewal, without charging you for it.
Who pays for flood damage?
Damage from extraordinary floods is paid by the Consorcio de Compensación de Seguros, but only if you have a valid insurance policy on the damaged property with the premium paid.
Do tenants need home insurance?
It is not required by law, but a contents and liability policy is cheap and protects you if you accidentally damage the flat or a neighbour’s property.
Disclaimer: This article is general information only and is not legal or insurance advice. Rules and policy terms differ between insurers and regions – always read the policy conditions and check with the insurer, a registered broker or the official source before you act.
Insurance
Car insurance in Spain for expats in 2026: what you need to know
Compulsory cover, terceros vs todo riesgo, foreign licences and no-claims history, and what to do after an accident in Spain.
Updated: October 2026
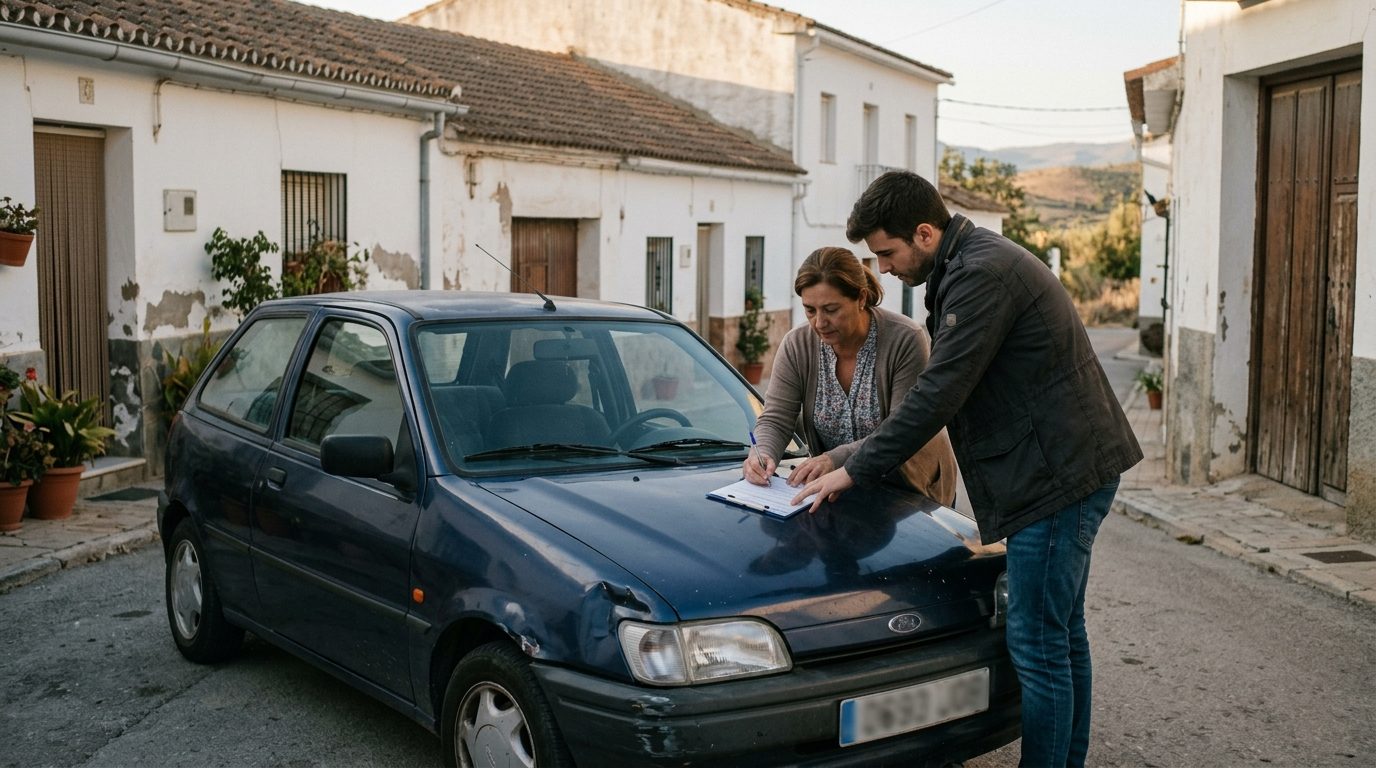
If you drive in Spain, whether in a car you brought from home or one you bought here, you need valid motor insurance from the first day. This guide is for expats and new residents who want to understand what is compulsory, which type of cover makes sense, how to use your no-claims history from abroad and what to do if you have an accident.
For an overview of all the main policies in Spain, from health to home, see our guide to insurance in Spain.
Online pharmacy & parapharmacySkincare, vitamins, baby care and more – delivered in SpainShop now
Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.Learn more →(ad)
Buying a home in Spain? Simulate your mortgageSee your monthly payment with Banco Sabadell’s mortgage simulator.Try the simulator →(ad)
A bank account for autónomos in SpainCuenta Clara Autónomos: no commissions, free debit and credit cards, opened online.See the account →(ad)
A European bank you open from your phonebunq: an EU-licensed bank with debit cards, managed fully in the app. Sign up in about five minutes.Get started →(ad)
A mobile bank account with no commissionsB100, the mobile bank from Abanca: everyday account and free debit card, all in the app.Get the app →(ad)
What the law requires
Every motor vehicle that is normally kept in Spain must have compulsory third-party liability insurance (seguro obligatorio de responsabilidad civil). This applies even if the car is parked and not being driven. The rules are set out in the motor liability law (Real Decreto Legislativo 8/2004), which was updated by Law 5/2025 to transpose the latest EU motor insurance directive.
The legal minimum cover is 70 million euros per claim for personal injury, regardless of the number of victims, and 15 million euros per claim for damage to property. The compulsory part only pays for harm you cause to other people and their property. It does not repair your own car.
Driving or keeping a car on the public road without insurance is a very serious offence. Fines are high (often reported at around 1,500 euros for a car on the road), and the police can immobilise the vehicle on the spot. If you cause an accident without insurance, the Consorcio de Compensación de Seguros pays the victims and can then claim the full amount back from you.
Types of car insurance in Spain
Spanish insurers sell three broad levels of cover. Names differ slightly between companies, but the structure is almost always the same.
| Type | What it usually covers | Suits |
|---|---|---|
| Terceros (third party) | Compulsory liability, plus voluntary liability, legal defence and often roadside assistance | Older or low-value cars |
| Terceros ampliado (third party plus) | As above, plus extras such as glass, fire and theft | Mid-value cars that are a few years old |
| Todo riesgo (fully comprehensive) | Damage to your own car as well, even if the accident is your fault | New or financed cars |
Fully comprehensive policies are often sold con franquicia, meaning with an excess you pay yourself on each claim for your own damage. A higher excess lowers the premium. If you finance or lease a car, the lender usually requires comprehensive cover for the length of the contract.
What affects the price
- Driver profile: age, years holding a licence and claims history.
- The car: value, power and how attractive it is to thieves.
- Where you live and park: postcode and whether the car sleeps in a garage.
- Named drivers: adding young or occasional drivers usually raises the price.
Foreign licence, foreign plates and your history abroad
Driving on a foreign licence
Most Spanish insurers will cover a driver with an EU licence without problems. With a UK or other non-EU licence, check first whether you are still allowed to drive on it as a resident, because insurance does not make an invalid licence valid. Our driving licence guide explains the exchange rules for EU, UK and non-EU drivers.
Cars on foreign plates
Compulsory liability insurance from any EU country is valid across the EU, so a visitor driving a car insured at home is legally covered in Spain. Voluntary extras such as comprehensive cover may be limited to a certain number of days abroad, so read your policy. Since 2 August 2021, UK-insured cars no longer need a green card in the EU.
Once you live in Spain, the car is generally expected to be registered here, and you will then need a policy from an insurer authorised in Spain. Many Spanish insurers will not insure a foreign-plated car long term, so plan the switch together with the registration. See our guide to registering a foreign car in Spain.
Using your no-claims history from abroad
Spanish insurers check your Spanish history in a shared industry file called SINCO, which records at-fault claims for the last five years. As a newcomer you will not appear there, so you may be quoted as a new driver unless you prove your record.
- Ask your previous insurer for a claims history statement covering the last five years. Under EU rules it must be issued within 15 days of your request.
- Send it with your quote request. A sworn translation is not always required, but ask the insurer what they accept.
- Compare several offers. Insurers are not obliged to give you a discount, but Spanish law says that when they use these certificates they must not discriminate on the basis of nationality or of the country where the certificate was issued.
What to do after an accident
Minor collisions in Spain are normally settled with the parte amistoso, officially the declaración amistosa de accidente (DAA), a joint report both drivers fill in at the scene. Keep a blank copy in the glovebox; your insurer can give you one, and many insurers also offer a digital version in their app.
- Make the scene safe: hazard lights, high-visibility vest and the V-16 warning light, and move the cars if they block traffic and nobody is hurt.
- Call 112 if anyone is injured or if the other driver refuses to cooperate.
- Fill in one DAA together: both drivers’ details, insurers and policy numbers, a sketch and the boxes that describe what happened. Both sign, and each keeps a copy.
- Do not sign anything you do not understand. If your Spanish is limited, write your version in your own language in the observations box.
- Take photos of the cars, plates, the road and any witnesses’ details.
- Report the accident to your insurer within 7 days, the general deadline in the Spanish insurance contract law, unless your policy gives you longer.
When both drivers sign the same DAA, the insurers can usually settle the claim quickly between themselves. If the other party disagrees or drives away, call the police so they can write a report.
Checking whether a vehicle is insured (FIVA)
Spain keeps a central database of insured vehicles called FIVA (Fichero Informativo de Vehículos Asegurados), managed by the Consorcio de Compensación de Seguros. Police use it at roadside checks, and it is updated daily.
Private individuals cannot search it freely online. If you have been in an accident and need to know the other vehicle’s insurer, you can apply to the Consorcio with the request form and a copy of the accident report or DAA. RACE explains the procedure and other ways to check. If the vehicle turns out to be uninsured or unidentified, the Consorcio can compensate you directly.
Tips for buying a policy
- Read the exclusions: check driving abroad, named drivers and what happens if an undeclared driver has an accident.
- Watch the renewal: policies renew automatically each year. To cancel, notify the insurer in writing before the renewal date.
- Keep proof in the car: police check insurance through FIVA, but carrying the receipt or a digital copy avoids discussions.
- Use a broker if needed: an independent corredor can compare insurers that accept foreign licences and foreign no-claims statements.
Useful links
- BOE: Law 5/2025 on motor liability insurance (consolidated text, Spanish)
- Your Europe: car insurance validity in the EU and claims history
- RACE: how to check if a car is insured (Spanish)
- Understanding insurance in Spain
- Driving in Spain: licence rules for EU, UK and non-EU drivers
- Registering a foreign car in Spain
FAQ: car insurance in Spain
Do I need insurance if my car is parked and not used?
Yes. A vehicle registered in Spain must have compulsory liability insurance even when it is not driven, unless it has been formally deregistered with the DGT.
Will a Spanish insurer accept my no-claims bonus from home?
Many will take it into account if you provide a claims history statement from your previous insurer, but they are not obliged to give a discount. Ask before you buy and compare several offers.
Do UK drivers need a green card in Spain?
No. The green card requirement for UK-insured vehicles in the EU ended on 2 August 2021. You still need valid insurance and should carry proof of it.
How long do I have to report an accident?
The general legal deadline is 7 days from the accident, unless your policy allows longer. Report it as soon as possible, even if you missed the deadline.
Disclaimer: This article is general information only and is not legal or insurance advice. Rules, cover and prices can change – always read your policy conditions and check with the insurer, a registered broker or the official source before you act.
 Ad
 A sea-view escape in MallorcaThe Donna Portals – stay by the sea with views over the Mediterranean.See prices →

 Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.✓ For autónomos and companies
✓ Sub-accounts for budgets and taxes
✓ Cards for your teamLearn more →(ad)
 A European bank you open from your phoneSign up with bunq in about five minutes.Get started →(ad)


Renting a car in Spain: what to check before you sign

Rebajas: when the sales start in Spain and your rights

Processionary caterpillars in Spain: a danger to dogs

Andalucía guide: cities, culture and life in southern Spain

Understanding the tax system in Spain

Marbella guide: areas, beaches and everyday life


-

 Tourist Info2 years ago
Andalucía guide: cities, culture and life in southern Spain
-
Banking & Finances2 years ago
Understanding the tax system in Spain
-
Tourist Info2 years ago
Marbella guide: areas, beaches and everyday life
-
Cost of Living2 years ago
Living on a small salary in Spain in 2026
-
Spanish System2 years ago
How the Spanish government works: state, regions, provinces and town halls
-
Tourist Info2 years ago
Benalmádena explained: Pueblo, Arroyo de la Miel and the coast
-
Cost of Living2 years ago
Family living costs in Spain in 2026: monthly budget and moving-in money
-
Legal Requirements & Documentation2 years ago
How to get your Spanish NIE number in 2026 – step by step