


Banking & Finances
Debit and credit cards in Spain: what newcomers should know
Debit vs credit, contactless and PIN rules, app codes, foreign card fees and what to do if your card is stolen in Spain.


Spain is a card country. You can tap your card for a coffee, a bus ticket or a parking machine, and many younger Spaniards rarely carry cash. For newcomers, the details still cause surprises: debit or credit, PIN requests, codes in your banking app, fees on a foreign card, and what to do if your card is stolen on the promenade. This guide explains the basics so you can pay safely from day one.
Debit and credit cards: the difference in Spain
- Debit card (tarjeta de débito): the money leaves your account straight away. This is the card most people use day to day, and it usually comes with your current account.
- Credit card (tarjeta de crédito): the bank lends you money up to a limit, and you repay it later. Car rental companies and some hotels prefer a credit card for the deposit.
- Prepaid card (tarjeta prepago): you load money first and can only spend that amount. Useful for teenagers or for online shopping with a limited budget.
With a credit card, check how you repay. Some cards take the full balance once a month. Others are revolving cards (tarjetas revolving), where you pay a fixed amount or a percentage each month and the rest keeps earning interest. The Banco de España warns that if the monthly payment is low, it may barely cover the interest, and the debt can grow like a snowball. Before you sign, ask how the instalments are calculated and use the bank’s simulator to see the total cost.
Most newcomers get their first Spanish debit card when they open an account. See our guide to opening a bank account in Spain. Digital banks are another option. For example, B100 (ad) is the digital bank of the Spanish bank Abanca, with an account you open in the app and a contactless Visa debit card. If you want a separate credit card, AXI Card (ad) is a credit card you apply for online. As with any credit card, read the repayment terms and interest rate before you use it.


 Online pharmacy & parapharmacySkincare, vitamins, baby care and more – delivered in SpainShop now
Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.Learn more →(ad)
 Buying a home in Spain? Simulate your mortgageSee your monthly payment with Banco Sabadell’s mortgage simulator.Try the simulator →(ad)
 A bank account for autónomos in SpainCuenta Clara Autónomos: no commissions, free debit and credit cards, opened online.See the account →(ad)
 A European bank you open from your phonebunq: an EU-licensed bank with debit cards, managed fully in the app. Sign up in about five minutes.Get started →(ad)
 A mobile bank account with no commissionsB100, the mobile bank from Abanca: everyday account and free debit card, all in the app.Get the app →(ad)


Contactless payments and when you need your PIN
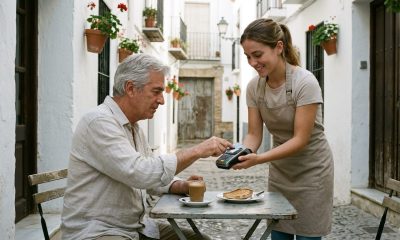
Almost every shop, bar and taxi in Spain accepts contactless payments with a card or a phone wallet. Small payments usually go through without a PIN. In 2020, banks in Spain began raising the no-PIN limit from €20 to €50, in line with a European Banking Authority recommendation. Your bank can tell you the exact limit on your card.
Under EU payment rules, the card terminal may still ask for your PIN on a small payment. This happens after several contactless payments in a row without a PIN (more than five), or once they add up to more than €150. This is normal and does not mean your card is blocked.
Strong authentication: those codes in your app
Since the EU’s PSD2 rules came in, online card payments and many banking actions need strong customer authentication. This means two separate proofs out of three types:
- Something you know: a password or PIN.
- Something you have: your phone, which receives an SMS code or a notification in the bank’s app.
- Something you are: a fingerprint or face scan.
Each code works for one payment only. Small online payments (under €30) can be exempt, but only up to a total of €100 or five payments since your last authentication. Two practical tips: keep your Spanish phone number up to date with your bank, and never give a code to anyone who calls you. Your bank will not phone you to ask for an authentication code.


Using a foreign card in Spain
Your home card will normally work in Spain, but fees can add up, especially outside the euro area.
- Pay in euros: when a terminal or ATM offers to charge you in your home currency, choose euros. This option is called dynamic currency conversion, and the exchange rate is set by the shop’s or ATM’s provider, which is often worse than your own bank’s rate.
- ATM fees: according to the Banco de España, the ATM must show any fee on screen before you take the cash, and you can cancel and look for another machine. The ATM owner cannot charge you directly. It passes the fee to your card issuer, which may pass it on to you.
- Your own bank’s charges: check your home bank’s fees for foreign currency payments and cash withdrawals before you rely on that card every day.
For paying friends, splitting bills or small shops, many people in Spain use Bizum instead of cards. It needs a Spanish bank account. Read our guide to Bizum and mobile payments.
If your card is lost, stolen or used for fraud
Act fast. The Banco de España’s advice is:
- Block the card immediately in your bank’s app, on its website or by phone. Save the emergency number in your phone now, not after the theft.
- Report it to the Policía Nacional, the Guardia Civil or a court. Our guide to the police in Spain explains who to contact.
- Check your account for payments you did not make, and ask your bank to reverse any made after the loss or theft. If you have insurance for your card or belongings, tell the insurer too.
Once you have told the bank, you are not responsible for later payments you did not make. Before you notify the bank, you can be liable for up to €50, unless you were negligent with the card or PIN. Under Spain’s payment services law, you must report an unauthorised payment without undue delay, and at the latest 13 months after the date it was debited.
Remember that fraudsters do not need your physical card. The number, expiry date and security code are enough for online payments, so be careful with text messages and emails that ask you to “verify” your card.
FAQ: cards in Spain
Should I pay in euros or my home currency in Spain?
Choose euros. If you pick your home currency, the shop’s or ATM’s provider does the conversion, usually at a less favourable rate than your own bank’s.
Why does the terminal ask for my PIN on a small payment?
EU rules require strong authentication after more than five contactless payments without a PIN, or once they add up to more than €150. Enter your PIN and the counter resets.
How much can I lose if my card is stolen?
Before you notify your bank, up to €50, unless you acted with negligence. After you notify it, the bank covers payments you did not make. Block the card straight away.
Is a revolving credit card a good idea?
Be careful. With low monthly payments, the debt can last a long time and cost a lot in interest. Check the repayment method and the total cost before you sign.
Useful links
- Banco de España: fraudulent card use (Spanish)
- Banco de España: ATM fees (Spanish)
- Banco de España: what revolving cards are (Spanish)
Disclaimer: This article is general information, not legal or financial advice. Rules and prices change, so check with the official source before you decide. Links marked “(ad)” are affiliate links – NewInSpain may earn a commission at no extra cost to you.


 Ad
 A sea-view escape in MallorcaThe Donna Portals – stay by the sea with views over the Mediterranean.See prices →

 Vivid BusinessA business account for freelancers and companies in SpainOpen your account online, with sub-accounts and cards for your team.✓ For autónomos and companies
✓ Sub-accounts for budgets and taxes
✓ Cards for your teamLearn more →(ad)
 A European bank you open from your phoneSign up with bunq in about five minutes.Get started →(ad)


Debit and credit cards in Spain: what newcomers should know

How to start playing golf on the Costa del Sol

Setting up a business in Spain: types of company and what you need in 2026

Andalucía guide: cities, culture and life in southern Spain

Marbella guide: areas, beaches and everyday life

Living on a small salary in Spain in 2026


-

 Tourist Info2 years ago
Andalucía guide: cities, culture and life in southern Spain
-
Tourist Info2 years ago
Marbella guide: areas, beaches and everyday life
-
Cost of Living2 years ago
Living on a small salary in Spain in 2026
-
Banking & Finances2 years ago
Understanding the tax system in Spain
-
Spanish System2 years ago
How the Spanish government works: state, regions, provinces and town halls
-
Tourist Info2 years ago
Benalmádena explained: Pueblo, Arroyo de la Miel and the coast
-
Cost of Living2 years ago
Family living costs in Spain in 2026: monthly budget and moving-in money
-
Insurance2 years ago
Understanding insurance in Spain: a 2026 guide for expats