


Banking & Finances
Getting a mortgage (hipoteca) in Spain in 2026
How Spanish mortgages work for residents and non-residents in 2026: how much banks lend, fixed vs variable rates, costs, documents and the signing process.

Updated: October 2026
Buying a home in Spain with a Spanish mortgage is very possible as a foreigner, but the rules and costs differ from what many people know at home. This guide is for both residents and non-residents. It explains how much banks usually lend, how fixed and variable rates work, which costs you pay and what happens on signing day.
Resident or non-resident: how much can you borrow?
Spanish banks lend a percentage of the purchase price or the official valuation (tasación), whichever is lower. This is called the loan-to-value, or LTV. Your tax residence makes a big difference:
| Tax residents in Spain | Non-residents | |
|---|---|---|
| Typical maximum LTV | Up to around 80% for a main home | Usually around 60–70% |
| Income checked | Spanish payslips, tax returns, contract | Foreign income, tax returns, credit reports |
| Typical term | Up to 30 years (often until age 70–75) | Often shorter, around 20–25 years |
These are market practices, not legal limits, so each bank decides. Most lenders also want your total monthly debt repayments to stay below roughly a third to 40% of your net income. On top of the deposit, budget about 10–15% of the price for taxes and purchase costs, as banks rarely finance these.
Fixed, variable or mixed rate
- Fixed (fijo): the same rate for the whole loan. Predictable payments, which many newcomers prefer.
- Variable (variable): a margin (diferencial) added to the 12-month Euribor, reviewed usually every six or twelve months. Your payment goes up or down with the index.
- Mixed (mixto): fixed for the first years, then variable.
Euribor moves with European interest rates and changes every day. Check the latest official monthly figure from the Banco de España before you compare offers, and ask the bank to show what your payment would be if Euribor rose by one or two points. Banks often reduce the margin if you take extra products such as home insurance, life insurance or a salary deposit. Compare the TAE (APR), which includes these costs, not just the headline rate.
What a mortgage costs and who pays
Since the 2019 mortgage law (Ley 5/2019), the costs of setting up a mortgage are split between you and the bank:
| You pay | The bank pays |
|---|---|
| Property valuation (tasación) | Notary fees for the mortgage deed |
| Your own copy of the deed, if you ask for one | Land registry fees for the mortgage |
| Opening fee, if the offer includes one | Gestoría (paperwork agency) |
| Stamp duty (AJD) on the mortgage |
This is only the mortgage. The purchase itself has separate costs that you pay: transfer tax (ITP) on resale homes, or VAT plus stamp duty on new builds, as well as notary and registry fees for the sale deed. Rates depend on the region. See our guide to property taxes for foreign owners for the yearly taxes once you own the home.
Early repayment fees are capped
For home loans to individuals signed since 16 June 2019, the maximum fees for paying off early are:
- Variable rate: 0.25% in the first 3 years or 0.15% in the first 5 years (depending on the contract), then nothing.
- Fixed rate: 2% in the first 10 years, then 1.5%.
Calculate your monthly payment and cash needed
Mortgage and buying-cost calculator
Estimate your monthly payment and how much cash you need to buy a home in Spain. All figures are estimates.
Estimated monthly payment
Loan amount: –
Total interest over the term: –
Rates, taxes and fees vary by region, bank and personal situation. This calculator is a guide only and not a mortgage offer or financial advice. Ask a bank, mortgage broker or independent lawyer for exact figures. Read more: getting a mortgage in Spain and buying costs in Spain.
Documents you will need
- Passport and NIE (foreigner identification number)
- Recent payslips and employment contract, or two years of accounts if self-employed
- Your latest income tax returns (Spanish or from your home country)
- Bank statements for the last six months, showing savings for the deposit
- Details of other loans and, for non-residents, a credit report from your home country
- The reservation or deposit contract for the property
Documents in other languages may need an official translation. You will also need a Spanish bank account for the repayments; our guide to opening a bank account in Spain explains how.
From application to signing at the notary
- Pre-approval: the bank checks your income and gives an indicative offer.
- Valuation: an approved valuer inspects the property. The loan is based on this value if it is lower than the price.
- Binding offer (FEIN): the bank gives you the standard European information sheet and the draft contract at least 10 calendar days before signing.
- Free notary meeting: before signing, you meet the notary you have chosen, who checks that you understand the terms. This advice is free of charge.
- Completion: you sign the purchase deed and mortgage deed at the notary, usually on the same day, and the funds are released to the seller.
If you do not speak Spanish well, bring a sworn interpreter or an independent lawyer. Many buyers use a mortgage broker, which can help non-residents in particular, but check how the broker is paid before you commit.
Useful links
- Banco de España: which mortgage costs you pay
- Banco de España: early repayment fees
- Property taxes for foreign owners in Spain
- Opening a bank account in Spain
- Investment strategies for expats in Spain
FAQ: mortgages in Spain
Can a non-resident get a mortgage in Spain?
Yes. Most Spanish banks lend to non-residents, but usually only around 60–70% of the value, so you need a larger deposit and stronger proof of income.
How much deposit do I need?
As a resident, plan for at least 20% of the price plus 10–15% for taxes and costs. Non-residents typically need 30–40% plus costs.
Do I have to buy the bank’s insurance?
Home insurance covering the building is required, but you can usually buy it elsewhere. Life insurance and other products are often optional and offered in exchange for a lower margin, so compare the total cost.
Is my income in pounds or dollars a problem?
Not necessarily, but banks may lend less to allow for exchange-rate risk, and your repayments in euros will cost more or less as the currency moves.
Disclaimer: This article is general information only and is not financial or legal advice. Interest rates, lending criteria and costs change often – always check the current terms with your bank or an independent adviser before you sign.
Banking & Finances
Bizum and mobile payments in Spain: a guide for newcomers
How Bizum works, how to set it up with a Spanish bank, what the 2026 Hacienda reporting rules mean, how to avoid scams and how else to pay by phone in Spain.

Updated: October 2026
Within a week of arriving in Spain, someone will ask you to “hacer un Bizum”. Splitting a dinner bill, paying your share of a birthday present or settling up with the padel group – Spaniards send small amounts by phone all the time. This guide is for newcomers who want to join in. You will learn how Bizum works, how to set it up, what the 2026 tax reporting rules mean for you, how to avoid the common scams and which other mobile payment options are widely used.
What Bizum is and how it works
Bizum is an instant payment service created by Spanish banks. It lives inside your bank’s own app: you send money to a mobile phone number instead of an IBAN, and it lands in the other person’s bank account within seconds. There is no separate wallet to top up – the money moves straight from account to account.
- Send money: choose a contact, enter the amount and a short concept, then confirm.
- Request money: ask a contact to pay you. They must accept the request before any money moves.
- Pay online: many Spanish web shops offer Bizum at checkout – you confirm the payment in your bank app instead of typing card details.
- Donate: many charities and NGOs accept donations by Bizum.
For everyday use between people it is generally free, but your bank sets the conditions, so check your account terms.
How to set up Bizum
You need an account at a bank that offers Bizum – most traditional Spanish banks do, as well as some online banks with a Spanish IBAN. Foreign accounts and many international money apps do not support it, so check before you choose a bank. Our guides on opening a bank account and the best banks for expats can help.
- Get a Spanish mobile number. Most banks link Bizum to a Spanish number – see our guide to mobile providers.
- Open your bank app and look for “Bizum” in the menu or payments section.
- Register your phone number and choose the account Bizum should use.
- Accept the terms and confirm with the code your bank sends you.
- Check your limits in the app. Bizum and each bank set maximum amounts per payment, per day and per month. If you need to move a large sum, use a normal bank transfer instead.
Each phone number can be linked to one account at a time. If you change bank, deregister Bizum at the old one first, then register at the new one.
Bizum and Hacienda: what changed in 2026
Headlines about “Hacienda watching Bizum” worried many people. Here is what actually changed:
- The rule: Royal Decree 253/2025 updated the information that banks and payment providers must send to the Agencia Tributaria. The new obligations apply from 1 January 2026.
- Who is reported: businesses and professionals (empresarios and profesionales) who receive payments by Bizum. Banks send monthly, aggregated figures – not every single payment.
- Private individuals: Bizum payments between friends and family are not part of this reporting, and Hacienda has stated that Bizum payments between private individuals do not have to be declared.
One important caveat: income is income, whatever the payment method. If you are self-employed, rent out a room or sell things as a regular activity, money received by Bizum must be declared like any other income. If you are unsure, read our guide to the Spanish tax system and ask a gestor.
How to avoid Bizum scams
Bizum payments are instant and usually cannot be reversed, which makes them attractive to fraudsters. The most common tricks:
- The fake “request”: a buyer on a second-hand app says they will “send you a Bizum”, but actually sends a request. If you accept it, you pay them. Read every screen carefully – a request asks you to send money.
- Fake bank calls or texts: nobody from your bank will ask for your passwords or confirmation codes. Hang up and call the number on your card.
- “Wrong number” payments: a stranger says they sent you money by mistake and asks you to return it. Check your actual account balance and contact your bank instead of sending anything.
- Deposits for flats or cars you have not seen: never pay a deposit by Bizum to someone you have not met for something you have not checked. Our renting guide explains safer ways to pay.
If you are scammed, contact your bank immediately and report it to the police – the sooner, the better the chance of stopping the money.
Other mobile payments in Spain
Bizum is for paying people and some web shops. In physical shops, other methods dominate:
| Method | Best for | Good to know |
|---|---|---|
| Bizum | Paying friends, small businesses, online shops | Needs a Spanish bank account offering Bizum |
| Contactless card | Shops, bars, supermarkets, transport | Accepted almost everywhere; may ask for your PIN above a certain amount |
| Apple Pay, Google Pay and similar | Same as contactless card | Your card must be supported by your bank |
| Bank transfer | Rent, deposits, larger amounts | Gives a clearer paper trail |
| Cash | Markets, small bars, tips | Still useful in villages and at local fiestas |
Carry a little cash anyway: some small bars, market stalls and village shops prefer it, and card terminals occasionally fail. Our cultural differences guide covers other everyday surprises.
Useful links
- Legálitas – Bizum and Hacienda: 2026 changes (Spanish)
- HelpMyCash – who the 2026 Bizum reporting affects (Spanish)
- El Español – Bizum between individuals does not need declaring (Spanish)
- How to open a bank account in Spain
- The best banks in Spain for expats
FAQ: Bizum
Can I use Bizum with a foreign bank account?
Generally not. Bizum works through participating banks with Spanish accounts, so you need a Spanish IBAN at a bank that offers it.
Is Bizum free?
Payments between individuals are usually free, but each bank sets its own conditions. Businesses that accept Bizum may pay fees under their merchant agreement.
Can I cancel a Bizum I sent by mistake?
Usually not, because payments are instant. Ask the recipient to send it back and contact your bank if they do not. Payments to numbers not registered in Bizum may stay pending for a short time and can then be cancelled.
Will Hacienda tax the Bizums my friends send me?
No – Bizum payments between private individuals are not reported and do not have to be declared. Money linked to a business, professional activity or rental income is a different matter and must be declared.
Disclaimer: This article is general information only and is not financial or tax advice. Bank conditions, limits and tax rules can change – check with your bank and the Agencia Tributaria, and ask a gestor or tax adviser about your own situation.
Banking & Finances
Sending money abroad from Spain: how to find the cheapest way
Banks, online transfer services and cash remittance shops compared: what sending money abroad from Spain really costs and how to check before you pay.

Updated: October 2026
Whether you are paying a mortgage back home, supporting family, moving savings for a property purchase or simply paying a bill in another country, sending money out of Spain can cost far more than it needs to. This guide compares the main types of provider in a neutral way, explains where the hidden costs are and shows how to work out the real price of a transfer before you send it.
First question: euros or another currency?
The cost of a transfer depends far more on where the money is going and in which currency than on which bank you use.
Euros to another SEPA country
If you send euros to an account in another country of the Single Euro Payments Area (SEPA), which includes the EU and countries such as Norway, Switzerland and the UK, the transfer works like a domestic one. Under EU rules, a cross-border euro transfer within the EU cannot cost more than the same transfer inside Spain, and many Spanish banks do not charge for online transfers at all.
Two newer EU rules also help:
- Instant transfers at the same price: since 9 January 2025, banks in the euro area cannot charge more for an instant euro transfer than for a standard one. Instant transfers arrive within seconds, every day of the year.
- Verification of payee: since 9 October 2025, your bank must check whether the name you enter matches the IBAN before you send, and warn you if it does not. This helps protect you from scams.
Branch transfers can still carry a fee, so doing it in your app or online banking is usually cheapest.
Other currencies or countries outside SEPA
Sending money to the US, Morocco, Colombia or anywhere in another currency, including pounds to a UK account, is where costs add up. You may pay:
- An upfront fee charged by your provider.
- An exchange-rate margin: the difference between the rate you get and the mid-market rate (the rate you see on financial news sites). This is often the biggest cost and the least visible.
- Intermediary and receiving fees: international SWIFT transfers can pass through correspondent banks that take a cut, and the receiving bank may charge too.
When a bank asks who pays the charges, the usual options are SHA (shared: you pay your bank, the recipient pays theirs), OUR (you pay all charges) and BEN (the recipient pays everything). If the exact amount must arrive, for example a rent or invoice, check which option you choose.
The main types of provider compared
Fees and rates change constantly and depend on the amount and destination, so this table compares how each type of provider usually works rather than quoting prices.
| Provider type | Typical strengths | Things to watch |
|---|---|---|
| Traditional Spanish banks | Familiar, good for euro SEPA transfers, often free online; useful for very large or regulated payments | Non-euro transfers can combine a fee with a wide exchange margin; branch transfers may cost extra |
| Online money transfer services (Wise and similar) | Usually show fee and exchange rate upfront, often close to the mid-market rate; fast for many currencies | Transfer limits and identity checks; compare the total for your amount and route |
| App-based and multi-currency accounts (Revolut and similar) | Hold and exchange several currencies in one app; convenient for regular small transfers | Plan limits, weekend or out-of-hours exchange surcharges and fair-use rules vary by plan |
| Cash remittance shops and services | Recipient can collect cash in many countries, including where bank accounts are less common | Fees and exchange margins can be high, especially for small amounts; always get a receipt |
| Currency brokers | Aimed at large sums such as a house purchase; can offer fixed or forward rates | Check they are authorised and how funds are protected; mainly worth it for large amounts |
No single type is always cheapest. For a small monthly amount to a family member, an online service or app may win. For €200,000 towards a property, a bank or broker quote may beat both. If you have not yet chosen a Spanish bank, see our guides to opening a bank account in Spain and traditional and online banks for expats.
How to compare the real cost
- Decide the exact amount you want to send and the currency the recipient needs.
- Check the current mid-market rate on a neutral financial site.
- Ask each provider for a quote showing the amount the recipient will receive, after all fees.
- Compare that figure, not the advertised fee. A “no fee” offer with a poor exchange rate can be the most expensive option.
- Check delivery time and whether the receiving bank charges for incoming international payments.
For transfers between EU currencies, providers have to show you the currency conversion charge before you confirm, which makes comparing easier.
Safety: check the provider is authorised
Any company that moves money for you in Spain must be authorised as a bank, payment institution or electronic money institution, either by the Banco de España or by another EU supervisor. You can check this in the Banco de España’s register of entities; for firms from other EU countries, the European Banking Authority’s register applies.
- Never send money to someone you have only met online, or because of an urgent call or message claiming to be your bank.
- Take the verification of payee warning seriously; transfers are hard to reverse once sent.
- For property purchases, confirm bank details by phone with your lawyer or notary using a number you already know, not one in an email.
Large amounts, paperwork and tax
Under anti-money-laundering rules, banks and transfer services can ask where large sums come from. Keep documents such as a sale contract, payslips or an inheritance deed to hand to avoid delays.
Sending money abroad is not taxed as such, but the money itself may have tax consequences: gifts can fall under Spanish gift tax depending on the region, and if you are tax resident with accounts abroad you may need to report them on Modelo 720. Carrying cash instead of transferring it is rarely a good idea: amounts of €10,000 or more entering or leaving Spain must be declared to the authorities.
Useful links
- Banco de España: Bank Customer Portal (information and complaints)
- Banco de España: unauthorised entities and how to check a provider (Spanish)
- OCU: instant transfers and verification of payee explained (Spanish)
- How to open a bank account in Spain
- The best banks in Spain for expats
FAQ: sending money abroad
Is it free to send euros from Spain to another EU country?
It costs the same as a domestic euro transfer with your bank, and many banks charge nothing for online transfers. Check your bank’s fee list for branch transfers.
Why did the recipient get less than I expected?
Usually because of the exchange-rate margin, intermediary bank fees or a receiving fee. Choosing OUR charges or a provider that guarantees the received amount avoids surprises.
Can I use Bizum to send money abroad?
Bizum is designed for payments between Spanish bank accounts. For international payments, use a bank transfer or a transfer service.
What if a transfer goes wrong?
Contact your provider immediately. If they do not resolve your complaint, you can escalate it to the Banco de España’s complaints service.
Disclaimer: This article is general information only and is not financial or tax advice. Fees, exchange rates and rules change frequently – always check the current terms with the provider and the official source before you send money.
Banking & Finances
How to handle Spanish tax audits and inspections as a foreigner
What happens when the Agencia Tributaria checks your taxes, how to respond to a letter, which deadlines apply and how to appeal as a foreign resident.
Updated: October 2026
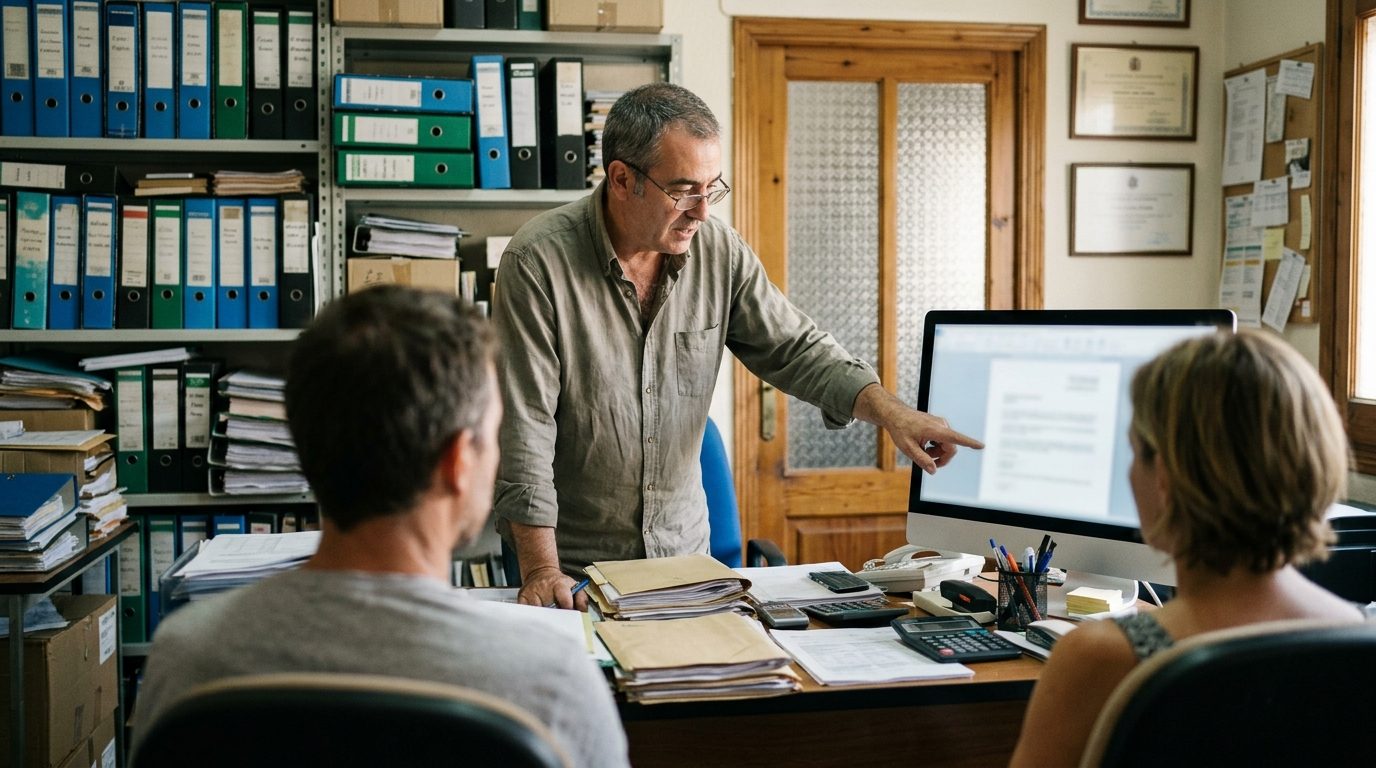
A letter from the Agencia Tributaria (AEAT) can be unsettling, especially if you are still learning how Spanish taxes work. This guide is for foreign residents, freelancers and property owners who have been contacted by the Spanish tax office, or want to be prepared. You will learn the difference between a simple check and a full inspection, how to respond, which deadlines matter and how to appeal.
Audit, check or inspection: what is the difference?
Most contact from the tax office is not a full audit. Spanish tax law (Ley 58/2003, General Tributaria) sets out several procedures, and it helps to know which one you are in, because the rules and time limits differ.
- Requerimiento (request for information): the office asks you to send a document or explain an item on your return. Often this is the whole matter.
- Comprobación limitada (limited check): a desk review by the management department, usually about specific items such as a deduction, rental income or a missing return. The maximum duration is six months.
- Inspección (inspection): a deeper review carried out by the inspection department, which can cover several taxes and years. The general maximum duration is 18 months, extended to 27 months in certain larger or more complex cases.
The letter you receive states which procedure has been opened, which tax and which years are covered. Read that part first.
Why foreigners get contacted
Foreigners are not targeted as a group, but some situations are more likely to trigger questions. The tax office cross-checks your return with data from banks, employers, notaries, land registries and, through automatic exchange of information, tax authorities in other countries.
- Foreign income (pensions, salaries, dividends) that does not appear on your Spanish return
- Foreign bank accounts or assets that were not declared on Modelo 720 when required
- Rental income from a Spanish property that was not declared, or non-resident tax that was not paid
- Doubts about your tax residence, for example if you spend more than 183 days a year in Spain but file as a non-resident
- Freelance (autónomo) invoices and VAT returns that do not match each other
How to respond step by step
- Check that it is genuine. Official notifications arrive by registered post or in your electronic mailbox at the AEAT Sede or DEHú. Be wary of emails or text messages asking you to click a link or pay; the tax office does not ask for card details that way.
- Note the deadline. The letter states how long you have to reply, often ten working days for a request for documents. If you are signed up for electronic notifications (mandatory for companies), a notification you do not open within ten calendar days is treated as delivered, so the deadline still runs.
- Gather the documents asked for and nothing more than what is relevant. Keep copies of everything you hand over.
- Reply through the official channel mentioned in the letter, usually the online Sede using your digital certificate, Cl@ve or a reference number, or in person with an appointment. Keep the registration receipt.
- Ask for more time if you need it. You can request an extension before the deadline ends, explaining why (for example, waiting for documents from abroad).
- Read the proposal carefully. At the end of a check you normally receive a proposal (propuesta de liquidación) and a period to submit comments (alegaciones) before the final decision.
Documents you may be asked for
- Spanish and foreign bank statements
- Employment contracts, payslips, pension statements or freelance invoices
- Proof of residence: padrón certificate, rental contract, utility bills, travel records
- A tax residence certificate from another country, if you claim to be resident there
- Purchase and sale deeds, receipts for deductible expenses and proof of foreign tax paid
The general limitation period for tax debts in Spain is four years, so keep your records for at least that long, counted from the end of the filing period of each return. Keep documents about property purchases and investments for as long as you own the asset, plus four years.
Possible outcomes and how to appeal
A check can end with no changes, or with an assessment (liquidación) of extra tax plus late-payment interest. If the office considers that you committed a tax offence, a separate penalty procedure is opened. Penalties can be reduced if you accept the assessment and pay within the deadline, so ask your adviser to calculate this before deciding whether to agree.
| Option | Where | Deadline |
|---|---|---|
| Recurso de reposición (optional) | The same office that issued the decision | One month from notification |
| Reclamación económico-administrativa | Regional or central economic-administrative tribunal (TEAR/TEAC) | One month from notification |
| Court appeal | Contentious-administrative courts | After the tribunal route is exhausted |
Appealing does not automatically stop the debt from being collected. To suspend payment while you appeal, you normally have to request it and offer a guarantee.
Modelo 720 and foreign assets
Tax residents must file Modelo 720 by 31 March if they hold more than 50,000 euros in one of three categories abroad: bank accounts, securities and investments, or real estate. In January 2022 the Court of Justice of the European Union ruled that the old, very high fixed penalties for late or missing 720 returns broke EU law, and Spain changed the system. However, undeclared foreign income can still be assessed, so if you have missed a 720 or not declared foreign income, get advice and consider correcting it voluntarily before the tax office contacts you.
Practical tips for expats
- Never ignore a letter, even if you have moved abroad. Keep your address up to date with the tax office.
- Get a digital certificate or Cl@ve so you can read notifications and reply online.
- Use a qualified adviser (asesor fiscal, gestor or tax lawyer) for inspections or anything involving foreign income. Many work in English.
- Stay factual and polite. Answer exactly what is asked and put your explanations in writing.
For the basics of income tax, residence and the main returns, read our guide to understanding the tax system in Spain.
Useful links
- Agencia Tributaria – official tax office website and online Sede
- Understanding the tax system in Spain
- Property taxes for foreign owners in Spain
- Investment strategies for expats in Spain
FAQ: Spanish tax audits
How do I know the letter is really from the tax office?
Genuine notifications arrive by registered post or in your electronic mailbox on the AEAT Sede or DEHú, and include a secure verification code. If in doubt, log in to the Sede yourself rather than clicking a link.
How many years back can the tax office check?
The general limitation period is four years from the end of the filing period for each return. It can be interrupted, for example when a check is opened.
Do I need to speak Spanish?
Procedures are run in Spanish (or a co-official language). If your Spanish is limited, use an adviser who can reply on your behalf with a signed authorisation.
What happens if I ignore the letter?
The procedure continues without you. You may be fined for not cooperating, and the tax office can issue an assessment based on the data it has and later collect the debt from your bank accounts.
Can I appeal if I disagree?
Yes. You can file a recurso de reposición with the same office or go straight to the economic-administrative tribunal, in both cases within one month of being notified.
Disclaimer: This article is general information only and is not tax or legal advice. Procedures and deadlines can change – always check your notification and the Agencia Tributaria, or consult a qualified adviser, before you act.
 Ad
✓ Sub-accounts for budgets and taxes
✓ Cards for your teamLearn more →(ad)

Private blood tests and health check-ups in Spain: how they work

Renting a car in Spain: what to check before you sign

Rebajas: when the sales start in Spain and your rights

Andalucía guide: cities, culture and life in southern Spain

Understanding the tax system in Spain

Marbella guide: areas, beaches and everyday life
-
 Tourist Info2 years ago
Andalucía guide: cities, culture and life in southern Spain
-
 Banking & Finances2 years ago
Understanding the tax system in Spain
-
 Tourist Info2 years ago
Marbella guide: areas, beaches and everyday life
-
 Cost of Living2 years ago
Living on a small salary in Spain in 2026
-
 Spanish System2 years ago
How the Spanish government works: state, regions, provinces and town halls
-
 Tourist Info2 years ago
Benalmádena explained: Pueblo, Arroyo de la Miel and the coast
-
 Cost of Living2 years ago
Family living costs in Spain in 2026: monthly budget and moving-in money
-
 Insurance2 years ago
Understanding insurance in Spain: a 2026 guide for expats